Publicité
Analysis
The Chagos Agreement: Sovereignty is not for sale, but what is the lease worth?
Par

Partager cet article
Analysis
The Chagos Agreement: Sovereignty is not for sale, but what is the lease worth?
⚫ The context
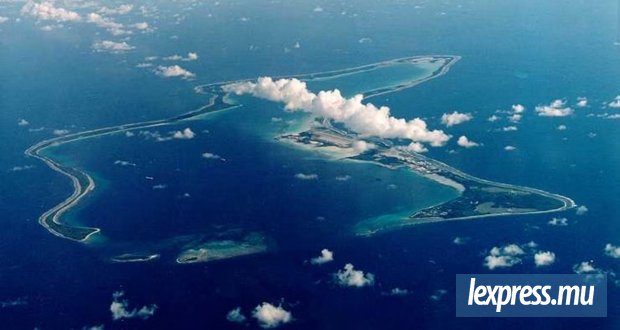
Let us be candid. For experienced political leaders such as Ramgoolam, Bérenger and Jugnauth, as well as for informed stakeholders who fully appreciate the significance of this critical issue, the central question has always been the undisputed sovereignty of Mauritius over the Chagos Archipelago and the preservation of our territorial integrity.
And rightly so.
Sovereignty is not negotiable. The financial package is a separate matter. It is the consideration associated with the lease-back arrangement. And finally there are security conditions governing the continued operation of the UK-US military facilities on Diego Garcia.
For many Mauritians, however, sovereignty can appear distant and abstract. Their immediate concern is the financial and broader economic dimension of the agreement, particularly at a time when the country faces significant economic and fiscal challenges. This concern has been amplified by repeated claims in sections of the British press and by politicians from Reform UK and the Conservative Party that the agreement is worth approximately GBP 35 billion, a colossal amount of money.
The agreement now faces a further challenge following objections raised by President Trump. Mauritius must continue to engage constructively with both the United Kingdom and the United States to identify a solution that preserves its sovereign rights while addressing legitimate security concerns, if any, relating to the future operation of the military base.
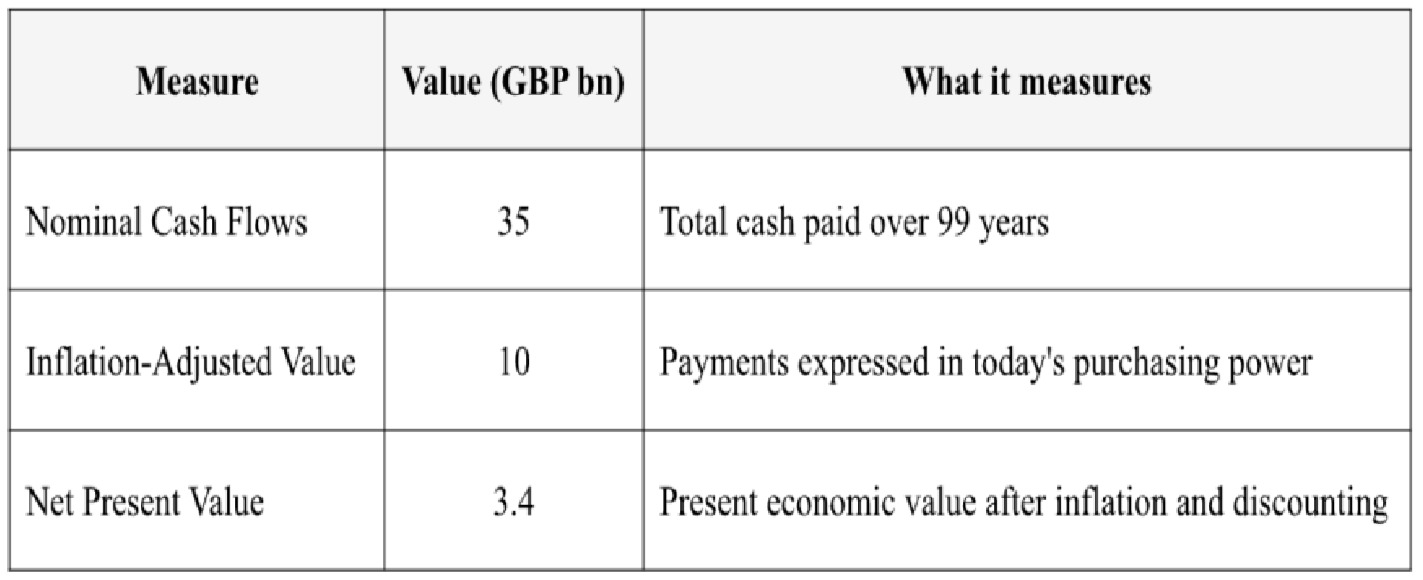 ■ The GBP 35 billion cited by opponents and the GBP 3.4 billion Net Present Value are not competing estimates but different valuations of exactly the same payment stream.
This article therefore examines the two issues at the heart of the current debate. First, whether a compromise can be found that preserves Mauritian sovereignty while accommodating American strategic interests. Second, whether the frequently cited figure of GBP 35 billion provides a meaningful measure of the value of the agreement. It argues that sovereignty is not for sale and that the financial package is payment for the leaseback arrangement. It also demonstrates that the headline figure of GBP 35 billion materially overstates the economic value of the financial package when assessed using established principles of economic and financial valuation.
⚫ The undisputed sovereignty of Mauritius
The Chagos Agreement has attracted criticism on two principal grounds: sovereignty and cost. For Mauritius, sovereignty was never a commodity to be negotiated or traded. It was and remains a matter of principle, grounded in international law, successive international decisions and the completion of the decolonisation process. Over time, legal, diplomatic and political developments increasingly reinforced Mauritius’ claim to sovereignty over the Chagos Archipelago, making its restoration a national imperative rather than a subject for commercial bargaining.
The agreement therefore represents a carefully balanced settlement. The United Kingdom formally recognises Mauritian sovereignty over the Archipelago while securing, through a long-term lease, the continued operation of the strategically important UK-US military base on Diego Garcia for an initial period of 99 years, with the possibility of a further 40-year extension.
It is essential to distinguish between these two elements. Sovereignty is the objective and is nonnegotiable. The financial package is the consideration for the lease-back arrangement that enables the continued operation of the military base on Mauritian sovereign territory. The real debate is therefore not about the value of sovereignty, which is beyond price, but about the value of the leaseback arrangement and the level of compensation associated with it.
Mauritius remains sovereign throughout the duration of the agreement. The lease grants extensive operational rights to the United Kingdom and the United States, but it does not transfer sovereignty. At the end of the lease period, Mauritius retains the sovereign right to determine the future of the arrangement, although the geopolitical realities at that time will inevitably influence such a decision.
⚫ Could the third component of the agreement break the logjam ?
The United Kingdom has signed the agreement with Mauritius and introduced the legislation required to ratify it. However, following objections raised by President Trump, the UK Government has paused the process while seeking a way forward.
If these objections are taken literally, there may be little room for compromise. President Trump appears to question the transfer of sovereignty from the United Kingdom to Mauritius. Yet Mauritius cannot and will not compromise on its sovereign rights.
If, however, the objections are viewed through the lens of President Trump’s well-known negotiating style, namely raising demands in order to maximise leverage before reaching a practical settlement, a compromise may still be possible.
Such a compromise cannot involve sovereignty. That issue has effectively been settled. The scope for negotiation lies elsewhere, in the operational, security and strategic arrangements governing the continued use of Diego Garcia. The existing agreement already provides substantial flexibility and safeguards for both the United Kingdom and the United States.
The key question is therefore not about revisiting sovereignty, but whether additional security, operational or strategic assurances could be crafted to accommodate President Trump’s concerns without diluting Mauritian sovereignty.
Frankly, the alternatives are considerably less attractive. They include postponing the agreement until after January 2029 in the hope of a different political climate in Washington, risking a change of government in the United Kingdom, criticising London for signing an agreement it is unable to implement, or engaging in a public confrontation with President Trump. None of these options appears particularly promising.
⚫ Could the recent trilateral USA-Denmark-Greenland agreement be a template for compromise?
The recent agreement between the United States, Denmark and Greenland offers an intriguing precedent, albeit with important qualifications. President Trump initially raised the prospect of acquiring Greenland outright or obtaining sovereignty over the territory on strategic grounds. The eventual agreement stopped well short of any transfer of sovereignty. Denmark retained full sovereignty and territorial integrity, while the United States secured extensive operational, security and strategic rights.
In practical terms, the agreement grants the United States many of the advantages it sought without conferring sovereignty. It allows the expansion and modernisation of existing facilities, the establishment of additional defence areas, broad military access, and significant influence over future security and strategic activities. It also provides the United States with a meaningful role in shaping decisions affecting sensitive investments and activities by strategic competitors in Greenland.
The lesson is straightforward. The United States did not obtain sovereignty, but it secured extensive functional control and strategic assurance. The UK-Mauritius agreement already contains substantial protections for both the United Kingdom and the United States. The remaining question is whether additional operational or security assurances could help bridge the current gap.
This inevitably raises a difficult question for Mauritius. If Denmark was able to preserve its sovereignty while accommodating US security concerns, could a similar approach help unlock the current impasse ? Would Mauritius be prepared to strengthen certain operational or strategic guarantees in order to secure implementation of an agreement that formally recognises its sovereignty?
Any answer depends on the nature of the assurances being sought. The Greenland agreement contains three provisions that deserve particularly careful scrutiny because they extend beyond traditional basing rights into the realms of strategic influence and economic oversight.
Article IX prevents non-NATO states from establishing military facilities or maintaining a persistent military presence in Greenland without US agreement. In practice, it excludes strategic competitors such as China and Russia from acquiring a military foothold.
Article X goes further by restricting investors from certain nonNATO and non-partner countries from obtaining control, significant influence or access to sensitive sectors where security concerns may arise. This extends beyond defence into strategic economic activities and investment policies.
Article XI may be the most consequential provision. The agreement has no fixed end date and may be amended only by mutual consent, creating a degree of permanence that goes well beyond the 99-year lease arrangement negotiated between Mauritius and the United Kingdom.
These provisions illustrate both the opportunities and the limits of any compromise. They show how far Denmark was prepared to go to accommodate American strategic concerns while preserving formal sovereignty. For Mauritius, enhanced operational flexibility and stronger security assurances may be negotiable. Sovereignty is not. Equally important, Mauritius would need to assess carefully whether arrangements similar to Articles IX, X and XI would be compatible with its long-term national interests, strategic autonomy and sovereign decision-making powers.
⚫ The financial consideration for the lease-back
The second issue concerns the financial dimension of the agreement. Public debate has been dominated by apparently conflicting figures ranging from GBP 35 billion, representing the undiscounted cash payments over 99 years, to GBP 3.4 billion, the Net Present Value (NPV) used by the UK Government
At first sight, these figures appear irreconcilable. In reality, they are simply different valuations of the same payment stream. The disagreement is therefore not about arithmetic but about methodology.
The crucial question is not how much money will be paid in aggregate between now and the end of the lease period. Rather, it is what those future payments are worth in today's money. This distinction is fundamental for an agreement that spans almost a century.
The financial package is the consideration paid for the lease-back arrangement that allows the continued operation of the Diego Garcia military base under Mauritian sovereignty. Its economic value should therefore be assessed using the same principles applied by governments, treasuries, investors and financial institutions when evaluating any long-term financial obligation.
To understand why the widely cited figure of GBP 35 billion materially overstates the economic value of the agreement, it is first necessary to examine the structure of the payment package and the different methods used to value it. Those distinctions lie at the heart of the current controversy.
⚫ The structure of the financial package
To understand the difference between the headline figure of GBP 35 billion and the Net Present Value of GBP 3.4 billion, it is necessary to examine the structure of the financial package itself.
The agreement comprises three distinct payment streams.
a. Annual Payments
This is by far the largest component of the package. It consists of an initial period of direct budget support followed by a much longer stream of annual lease payments. The payments are not indexed during the early years of the agreement but subsequently become linked to the UK GDP deflator.
b. Development Fund
A second component consists of development support payments spread over four seven-year cycles. Unlike the annual lease payments, the Development Fund is not indexed. Its nominal value remains unchanged, while its real purchasing power declines over time as inflation accumulates.
c. Chagossian Trust Fund
The third component is a one-off contribution to the Chagossian Trust Fund. It is neither recurring nor indexed to inflation.
This distinction is important because not all elements of the package are treated equally for valuation purposes. Some payments retain their nominal value, others are indexed only after a number of years, while still others are fixed throughout their duration. As a result, the aggregate cash flows must be adjusted for inflation and the time value of money before their true economic value can be assessed.
⚫ Three different measures of cost and revenue
Much of the debate surrounding the agreement stems from the fact that different valuation methods are being used to assess exactly the same payment stream.
Public discussion has largely focused on two figures: GBP 35 billion, frequently cited by opponents of the agreement, and GBP 3.4 billion, the Net Present Value used by the UK Government. In reality, official UK calculations identify three distinct measures of value.
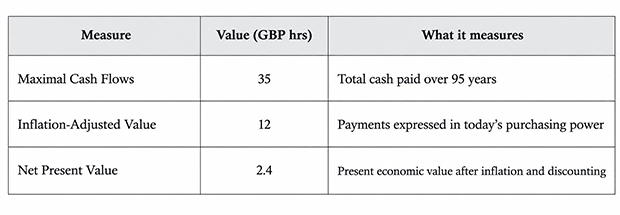
The three figures are different valuations applied to exactly the same payment stream.
These figures are not competing estimates. They are different valuations of the same payment stream. The first simply aggregates all future payments over the life of the agreement. The second adjusts those payments for inflation. The third goes one step further by recognising that money received or paid decades in the future is worth less than money today.
⚫ Why Net Present Value is the appropriate benchmark?
Some critics in the UK argue that the "true cost" is the nominal figure of GBP 35 billion. While politically attractive, this argument is economically misleading. For a short-term agreement lasting a few years, the distinction between nominal values and present values may not materially affect the outcome. However for a commitment spanning ninety-nine years, the distinction becomes fundamental. No serious assessment of government borrowing or pension obligations relies on undiscounted cash flows. The purpose of Net Present Value is precisely to provide a meaningful measure of the economic value of long-term commitments.
⚫ The financial market test: What would the payment stream be worth today ?
A simple way to assess the economic value of a long-term payment stream is to recognise what would an investor pay today to acquire the right to receive those future payments. Governments and major corporations frequently convert long-term revenue streams into upfront capital through securitisation or similar financial transactions. In such arrangements, investors do not pay the undiscounted sum of future payments. They pay the present value of those payments.
This principle lies at the heart of global capital markets. If Mauritius wished to monetise part or all of the future Chagos payment stream, it could theoretically engage leading international financial institutions such as Goldman Sachs, JPMorgan,Citibank,HSBC and Standard Chartered. None of these institutions would offer Mauritius GBP 35 billion today in exchange for a payment stream over 99 years. Indeed, they would estimate future payments, adjust for inflation, apply an appropriate discount rate and calculate the present value of the cash flows. The resulting valuation would be some variant of the Net Present Value and therefore much closer to GBP 3.4 b rather than to GBP 35 b.
⚫ Conclusion
The debate surrounding the Chagos Agreement has focused on two distinct issues. sovereignty and cost. On sovereignty, the agreement secures formal recognition of Mauritian sovereignty over the Chagos Archipelago while allowing the continued operation of the strategically important UK-US military base on Diego Garcia through a long-term lease arrangement. Sovereignty was the objective. It was never for sale and remains non-negotiable.
The current impasse should therefore be viewed primarily through the prism of security and operational arrangements rather than sovereignty. If a compromise is possible, it is more likely to be found in additional assurances to address President Trump’s strategic concerns, if any.
The second issue concerns the value of the lease-back arrangement. Here, the debate has been distorted by the repeated use of the headline figure of GBP 35 billion. While arithmetically correct, it is simply the undiscounted sum of payments spread over ninety-nine years. It is not a measure of their economic value. Once inflation and the time value of money are taken into account, the picture changes dramatically. The relevant benchmark becomes the Net Present Value, estimated by the UK Government at approximately GBP 3.4 billion. Hardly one tenth of the headline-grabbing figure of GBP 35 b.
Publicité
Publicité
Les plus récents