Publicité
Raising the Key Rate: Is the cure worse than the disease?
The high risks of fighting a supply shock with higher interest rates when growth, investment and exports are already weakening
Par

Partager cet article
Raising the Key Rate: Is the cure worse than the disease?
The high risks of fighting a supply shock with higher interest rates when growth, investment and exports are already weakening
1. The Central Bank's dilemma
The Bank of Mauritius faces a difficult balancing act. On the one hand, it must preserve price stability, maintain confidence in the rupee and prevent inflation expectations from becoming entrenched. On the other, it must consider the macroeconomic consequences of higher interest rates for economic growth, investment and exports and the microeconomic effects for households and businesses. These trade-offs have become increasingly challenging following the two 25-basis-point increases in the Key Rate since May 2026. It is worth recalling that the increase in the Key Rate to 4.5 per cent in February 2025, well before the Middle East conflict and the latest surge in geopolitical uncertainty, restored the policy rate to its pre-election level and effectively returned it to the level that had prevailed since 2022. The current debate therefore concerns the subsequent tightening undertaken since May 2026.
Central bankers distinguish between first-round imported inflation and second-round domestic inflation. First-round effects arise when higher international prices for fuel, food and imported goods are transmitted directly into the domestic economy. Second-round effects occur when those increases become embedded in wages, domestic prices and inflation expectations. The BOM's concern is that imported inflation may gradually become more generalised across the economy. However, the effectiveness of monetary policy depends critically on the source of inflation, its timing and the broader state of the economy.
2. Demand-side medicine for a supply-side ailment?
If inflation results from excessive domestic demand, higher interest rates are often the correct policy response. They moderate borrowing, slow consumption, curb investment and help bring demand back into line with productive capacity.
The current inflationary environment is fundamentally different.
Much of the pressure on prices originates from factors largely outside Mauritius's control, including higher energy and commodity prices, disruptions to global supply chains, shipping and freight costs and geopolitical tensions. These are characteristics of imported and cost-push inflation rather than demand-pull inflation. The distinction matters because monetary policy cannot directly address these shocks. Higher interest rates do not lower international oil prices, reduce freight costs, restore disrupted trade routes or increase global food production. They may weaken demand, but they cannot reverse the original source of the inflationary pressure.
The challenge becomes even greater when imported inflation coincides with weaker global demand, subdued domestic growth and a deteriorating investment and export climate. This increasingly appears to be the situation confronting Mauritius today. If the problem originates primarily on the supply side rather than from excessive demand, policymakers must be careful not to prescribe a remedy that weakens economic activity without materially addressing the underlying drivers of inflation.
3.Does the evidence support or contradict the two assertions of the Central Bank?
The Bank of Mauritius argues that inflation risks have become more significant than growth risks and that economic activity has strengthened. The broader evidence suggests a different picture, as shown in the table below on GDP growth, inflation and investment for the 2024-2026 period.
Mauritius's triple squeeze: slower growth, falling investment and rising inflation
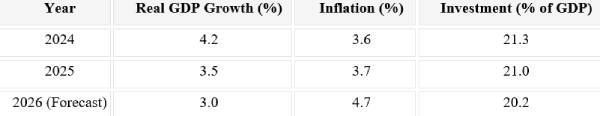
The direction of travel is unmistakable. There is a triple squeeze. Growth has slowed materially. Inflation is rising. Investment has fallen steadily as a share of GDP. Moreover, private-sector investment has weakened sharply and is expected to contract in 2026. More concerning, a growing share of investment is being directed towards real estate rather than activities that expand productive capacity and strengthen competitiveness. The picture becomes more worrisome when exports are considered. Goods exports are expected to decline by 2.3 per cent in 2026 following a fall in 2025. Growth in services exports is slowing, while export-oriented enterprises have recorded several years of weak performance. Taken together, these trends point to an economy experiencing a rare and uncomfortable combination of slower growth, declining investment, weakening exports and rising inflation.
4.The context could not be worse for households and businesses
Consumers and producers are already financially vulnerable as many are highly indebted and confront considerable economic headwinds. Households face a threefold pressure through an erosion of purchasing power caused by elevated prices, higher monthly mortgage and loan repayment costs and an additional reduction in disposable income. Producers are dealing with higher imported input costs, expensive energy and transportation and weaker demand. Raising interest rates increases their debt-servicing costs, makes working capital more expensive and reduces the financial viability of new investment. SMEs which have less access to affordable financing and fewer financial buffers are particularly exposed. When households are already squeezed by the cost of living and businesses are struggling with rising input costs and subdued sales, further monetary tightening can amplify rather than alleviate the economic damage caused by the external supply shock.
5. Timing matters: The risk of a policy mismatch
The timing of further tightening is particularly important because Mauritius is already facing a difficult external environment. Global growth is weakening, geopolitical tensions remain elevated and external demand is becoming increasingly uncertain for an economy that relies heavily on exports, tourism and foreign investment.
At the same time, the Government has embarked on fiscal consolidation through pension reform, cuts in social benefits, higher taxes for households and businesses, and a reduction in the VAT registration threshold for SMEs. Whether these measures are described as fiscal consolidation or austerity is ultimately less important than recognising their economic effects. They are already affecting disposable incomes, business activity and investment.
The key issue is not whether fiscal discipline or monetary tightening can be justified individually. It is whether their combined impact risks becoming excessively contractionary when growth is already weakening and inflation is being driven largely by external supply-side forces. The concern is amplified by policy lags. The full effects of fiscal consolidation may not yet be visible in growth, investment and export data. Additional monetary restraint could therefore reinforce a slowdown that is already underway. If fiscal and monetary policies become more restrictive simultaneously, weaker consumption, investment, exports and growth are likely to follow. Such a response may be justified in an overheating economy. However, current conditions point to subdued demand rather than excess demand. The danger is that economic activity is weakened without materially reducing the underlying sources of inflation.
6. Supply-side constraints are weakening growth potential
The current drought provides a vivid illustration of a broader challenge confronting Mauritius. Water shortages and supply restrictions have morphed into a significant economic constraint affecting households, agriculture, manufacturing, tourism and many service industries. Reduced water availability can lower output, increase operating costs and place additional pressure on food prices. Yet these challenges cannot be resolved through higher interest rates. Monetary policy cannot increase rainfall, replenish reservoirs, reduce network losses or expand storage capacity. These require investment, infrastructure upgrades and better resource management.
The country is also confronting demographic ageing, a shrinking workforce, skills shortages, weak productivity growth, climate vulnerabilities and growing competitive pressures. At the same time, the global economy is being reshaped by digitalisation, artificial intelligence and the resurgence of economic nationalism and protectionism. As countries place greater emphasis on domestic production and economic security, trade and investment flows are becoming more fragmented. For a small, open and export-led economy, weaker global demand and protectionist measures could affect exports, tourism and foreign direct investment. None of these challenges reflects excessive domestic demand. They are structural constraints that weaken productive capacity and limit long-term growth.
The reality is that the growth model that served Mauritius well for decades is becoming less effective. Equally concerning, no major new pillar of growth has emerged for a very long time. Future prosperity will depend increasingly on productivity gains, innovation, technological adoption, stronger skills, improved competitiveness and a shift towards higher-value-added goods and services.
Mauritius also remains highly dependent on imported fossil fuels and food products, two major channels through which external shocks are transmitted into domestic inflation. Reducing these vulnerabilities should become a strategic national objective. Accelerating the transition towards renewable energy, improving energy efficiency and promoting stronger demand-management measures would strengthen energy security while reducing exposure to volatile global markets. Likewise, strategic investments in climate-smart agriculture, storage facilities and food supply chains would improve food resilience and moderate future inflationary pressures.
Ultimately, the challenge is not simply to achieve higher growth. It is to transform the structure of the economy. If investment and exports continue to weaken while fiscal and monetary policies become more restrictive, Mauritius risks slowing the very transition needed to strengthen competitiveness, diversify exports and generate new engines of growth.
A more balanced policy mix is required than reliance on higher interest rates alone
Recognising the limitations of monetary policy does not mean abandoning the fight against inflation. It means acknowledging that Mauritius's challenges require a broader and more coordinated policy response. Monetary policy should continue to anchor inflation expectations while taking account of risks to growth, investment and exports. Fiscal policy should strengthen public finances without undermining productive investment, economic transformation and long-term growth. This requires greater focus on containing unnecessary expenditure, reducing wasteful spending, addressing costly implementation delays, rationalising overlapping public sector bodies and systematically implementing the recommendations of the Director of Audit. Fiscal consolidation should be achieved through higher efficiency and better expenditure management rather than by sacrificing priority investments in key infrastructure and skills development that are essential to the country's future competitiveness.
Exchange-rate policy also has an important role to play. In a small open economy, imported inflation reflects not only global commodity prices but also exchange-rate movements. Maintaining an orderly and competitive exchange-rate framework can help absorb external shocks while supporting exports and reducing pressure on interest rates as the primary instrument of adjustment.
Most importantly, structural reforms and supply-side policies must become the centrepiece of economic strategy. Mauritius needs to raise productivity, improve the business environment, strengthen workforce skills, encourage innovation, accelerate technology adoption and support export-oriented sectors.
The country must also diversify its sources of growth. No major economic pillar has emerged for many years. Future prosperity will require stronger capabilities in higher-value-added manufacturing, digital services, technology-enabled business services, renewable energy, blue economy and other knowledge-intensive activities capable of generating productivity gains, quality employment and foreign-exchange earnings.
Energy security, food resilience and water reliability should be viewed not as sectoral concerns but as central components of economic policy. Investments in renewable energy, climate adaptation, wastewater reuse, efficient water management and strategic food resilience are investments in competitiveness, resilience and long-term growth.
Ultimately, monetary, fiscal, exchange-rate and structural policies must reinforce rather than offset one another. No single policy instrument can simultaneously contain inflation, raise productivity, strengthen exports, improve competitiveness, enhance resilience and create new engines of growth.
Conclusion
The evidence increasingly suggests that Mauritius is not confronting an overheated economy driven by excessive demand. Instead, it faces a combination of slower growth, weakening investment, subdued exports, severe drought and inflation driven largely by external and supply-side factors. The risk is therefore not inflation alone. It is the emergence of a policy mix that weakens growth, discourages investment and slows economic transformation while leaving the underlying causes of inflation largely unchanged. If a fundamentally supply-side problem is treated primarily with demand-side instruments, the economic costs may ultimately outweigh the benefits.
Mauritius needs a broader strategy built around prudent monetary management, efficient fiscal consolidation, a competitive exchange-rate framework and ambitious structural reforms. Fiscal adjustment should focus on eliminating wasteful expenditure, improving delivery efficiency, rationalising public bodies and implementing the recommendations of the Director of Audit, while protecting critical investments in infrastructure, water security, renewable energy, climate resilience, skills and innovation. In the meantime policymakers should avoid inflicting further damage on an already weak economy characterised by low growth, declining investment, subdued exports and severe water shortages through additional increases in interest rates aimed at containing an external supply shock.
Publicité
Publicité
Les plus récents